LIVING IN THE UK ON A VISA
Visa mortgages
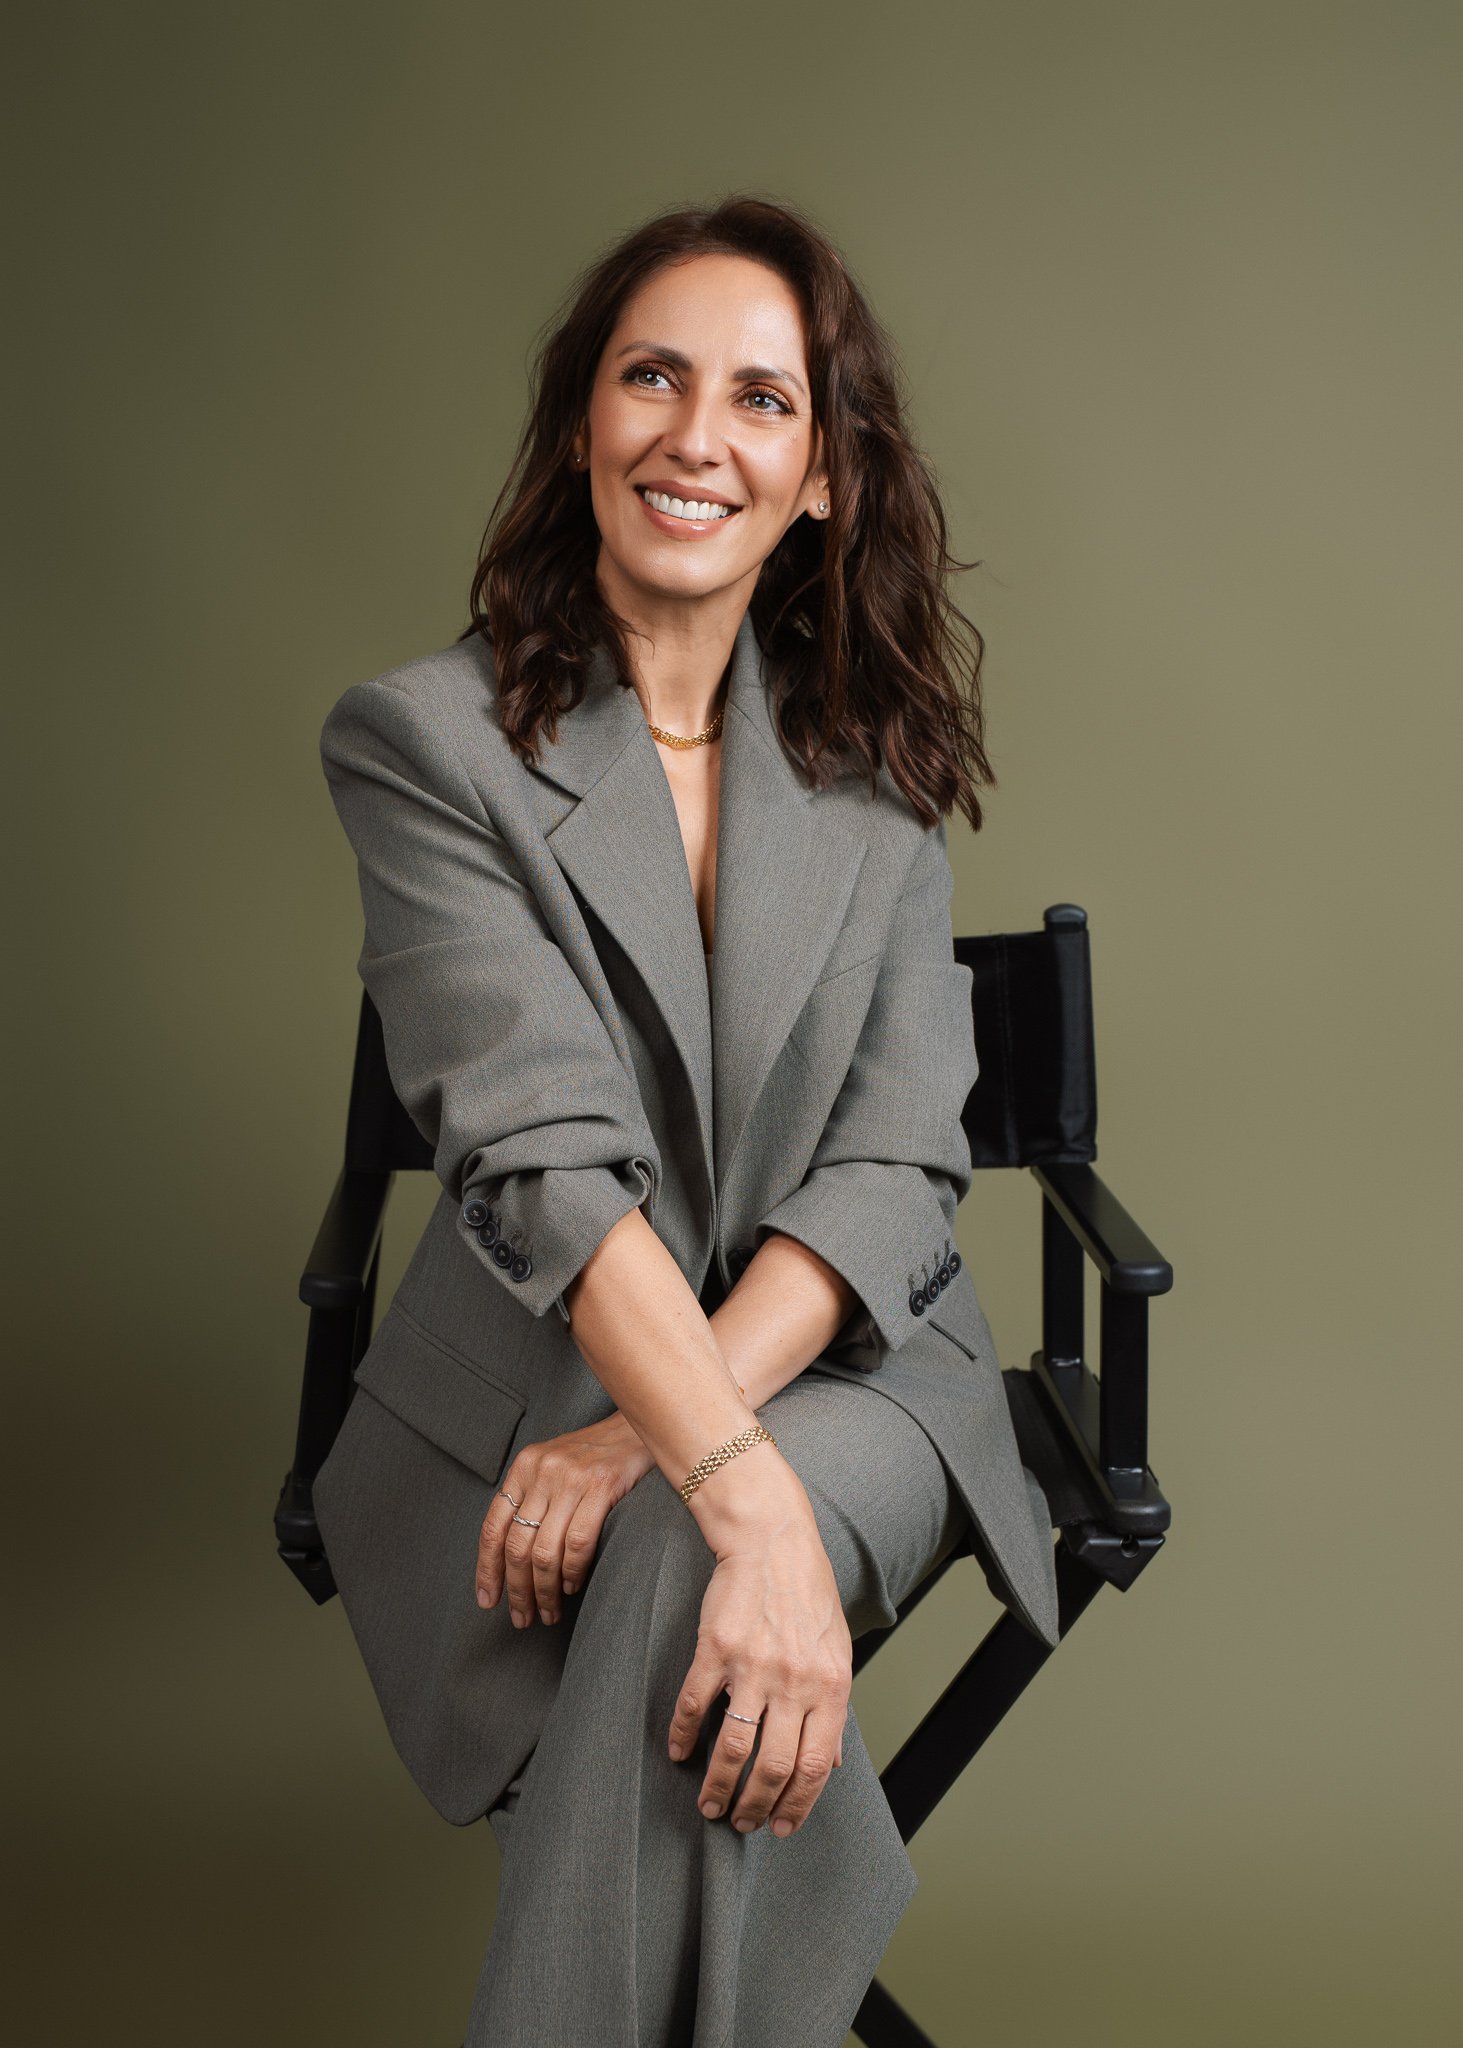
You live here, work here and pay your taxes here, so why should buying a home feel harder? Our adviser Galina Agintiene helps visa holders find lenders that understand their situation, often with smaller deposits than people expect.
★★★★★ 5.0 from 120+ Google reviews · FCA authorised · Whole of market
Who we help
Every visa mortgage depends on your visa type, how long you've been in the UK and your credit history. We help:
Skilled Worker visa holders
Including Health and Care Worker visas. The most widely accepted route for a visa mortgage, especially with a professional role and UK-taxed income.
Spouse and partner visas
Buying on your own or together with a partner who is a UK national or has settled status.
Settled and pre-settled status
With settled status or indefinite leave to remain, most lenders treat you like a UK resident. Pre-settled status opens up many lenders too.
Other visa types
Global Talent, Ancestry, BN(O) and others are accepted by fewer lenders, so knowing where to go matters even more.
What most people don't know
BUYING WITH A PARTNER
One visa, one settled partner? Deposits from 5%
If one of you is on a visa and the other is a British citizen or has settled status, some lenders assess you on their standard criteria, with deposits from as little as 5%. Many couples don't realise this and save for years longer than they need to.
BUYING ON YOUR OWN
On a visa? Some lenders accept a 10% deposit
You don't always need 25%. Some lenders offer a visa mortgage with a 10% deposit, depending on your visa, your income and how long you've been in the UK.
Every case is different. All mortgages are subject to lender criteria and affordability.
What lenders look at for a visa mortgage
✓ Your visa type and how long is left on it. Many lenders like around two years remaining, but some accept less
✓ Time in the UK and how long you've been in your job
✓ Your UK credit history. A thin credit file is the most common reason for a decline
✓ Your deposit. From 10% on a visa, and from 5% with a settled or British partner, or with settled status yourself
Build your UK credit file before your visa mortgage
Open a UK bank account, register on the electoral roll if you're eligible, put bills in your name and use a credit card you clear in full each month. Even a year of good UK history can open up more lenders and better rates.
Stamp duty for visa holders
Your stamp duty depends on where you've been living, not on your visa. If you've spent at least 183 days in the UK in the 12 months before buying, you'll usually pay the same rates as UK residents, and first time buyer relief can apply. If not, a 2% non-resident surcharge is added, which you may be able to reclaim later. We'll factor this into your visa mortgage plan from the start.
How we help with your visa mortgage
Galina knows which lenders accept which visas, how much time they need left on your visa and how they view a short UK credit history. We match you with the right lender first time, avoiding unnecessary declines, and guide you through every step. Prefer to talk in Lithuanian or Russian? Just ask.
What you'll need for a visa mortgage
✓ Passport and biometric residence permit or eVisa share code
✓ Proof of UK address
✓ Last 3 months' payslips and bank statements
✓ Your employment contract
✓ Proof of your deposit and where it came from
Visa mortgage FAQs
Can I get a mortgage on a Skilled Worker visa?
Yes. Skilled Worker and Health and Care Worker visas are widely accepted, and some lenders accept a 10% deposit, depending on your income, time in the UK and credit history.
My partner is British. Does that help?
Yes. If one of you is a British citizen or has settled status, some lenders apply their standard criteria, with deposits from as little as 5%.
How long do I need to have lived in the UK for a visa mortgage?
There's no single rule. Some lenders consider you from day one, while others want a year or two of UK residence. A longer UK history usually means more choice.
What if my visa expires soon?
Many lenders prefer around two years left on your visa, but some accept less, especially with a bigger deposit or proof you're renewing. Speak to us early so we can plan around your dates.
Can I get a visa mortgage with no UK credit history?
It's harder, but possible. Some lenders assess you manually using bank statements and employer references. Building a UK credit file as early as possible helps a lot.
Do visa holders pay extra stamp duty?
Not usually, if you've spent at least 183 days in the UK in the year before buying. Otherwise a 2% non-resident surcharge applies, which may be reclaimable later.
Buying your first home? See our first time buyer mortgages page. Official guidance: GOV.UK on stamp duty for non-UK residents.
Your home may be repossessed if you do not keep up repayments on your mortgage.
BOOK YOUR FREE CONSULTATION
On a visa and ready to buy?
Tell us your visa type, how long you’ve been in the UK and what you’d like to buy. We’ll show you which lenders fit and how much deposit you’ll need.
Free 30-minute consultation
✓ Pick a time that suits you
✓ Phone or video call
✓ No obligation to proceed
✓ Kalbame lietuviškai · Говорим по-русски